Sport is being financed like an asset class. But is it governed like one?
The rulebook for the NFL looks like financial architecture and other sports can learn from it. Image: Emilio Garcia/Unsplash
Ramya Krishnaswamy
Head of Institutional Communities; Executive Committee Member, World Economic Forum- The global sports economy generates $2.3 trillion a year, yet its governance structures lag behind those of more traditional asset classes.
- As institutional capital moves deeper into sport, investors are demanding clearer rules around ownership, risk and accountability.
- With the sports economy expected to reach $3.7 trillion by 2030, governance is becoming a question of growth, not just compliance.
Sport now generates $2.3 trillion a year and is forecast to reach $3.7 trillion by 2030. More than 345 clubs sit in multi-club investment structures, up from fewer than 60 a decade ago. This is not just a change in ownership, but in expectations of how sports assets are governed.
In August 2024, National Football League (NFL) owners voted to allow private equity firms to buy stakes in franchises, on highly prescriptive conditions. Approved funds must hold at least $2 billion in committed capital. None may put over 20% into a single team, hold stakes in more than six teams, or exit within six years. Only pre-vetted firms qualify.
Banks and insurers have used this rulebook for decades: a capital floor, a concentration ceiling, a minimum holding period, a vetted counterparty list. Nobody called it financial regulation, but the logic is familiar.
Forbes puts the average NFL franchise at 10.7 times revenue, up from 6.4 five years ago. In England’s Premier League, the top five clubs are valued at 6 to 8.3 times revenue; the rest mostly under four.
Relegation risk and media structures explain part of that gap, not all of it. Done well, governance turns fandom into cash flow institutional capital can underwrite.
Sport owners changed, but the operating system did not
Capital has transformed, but governance has been renovated rather than redesigned.
Sport has added transparency, safeguarding policies, ethics codes and audit committees. Yet the underlying architecture is unchanged: the people who govern are elected by those they govern.
These are membership associations designed around representation, not listed companies built for shareholder oversight.
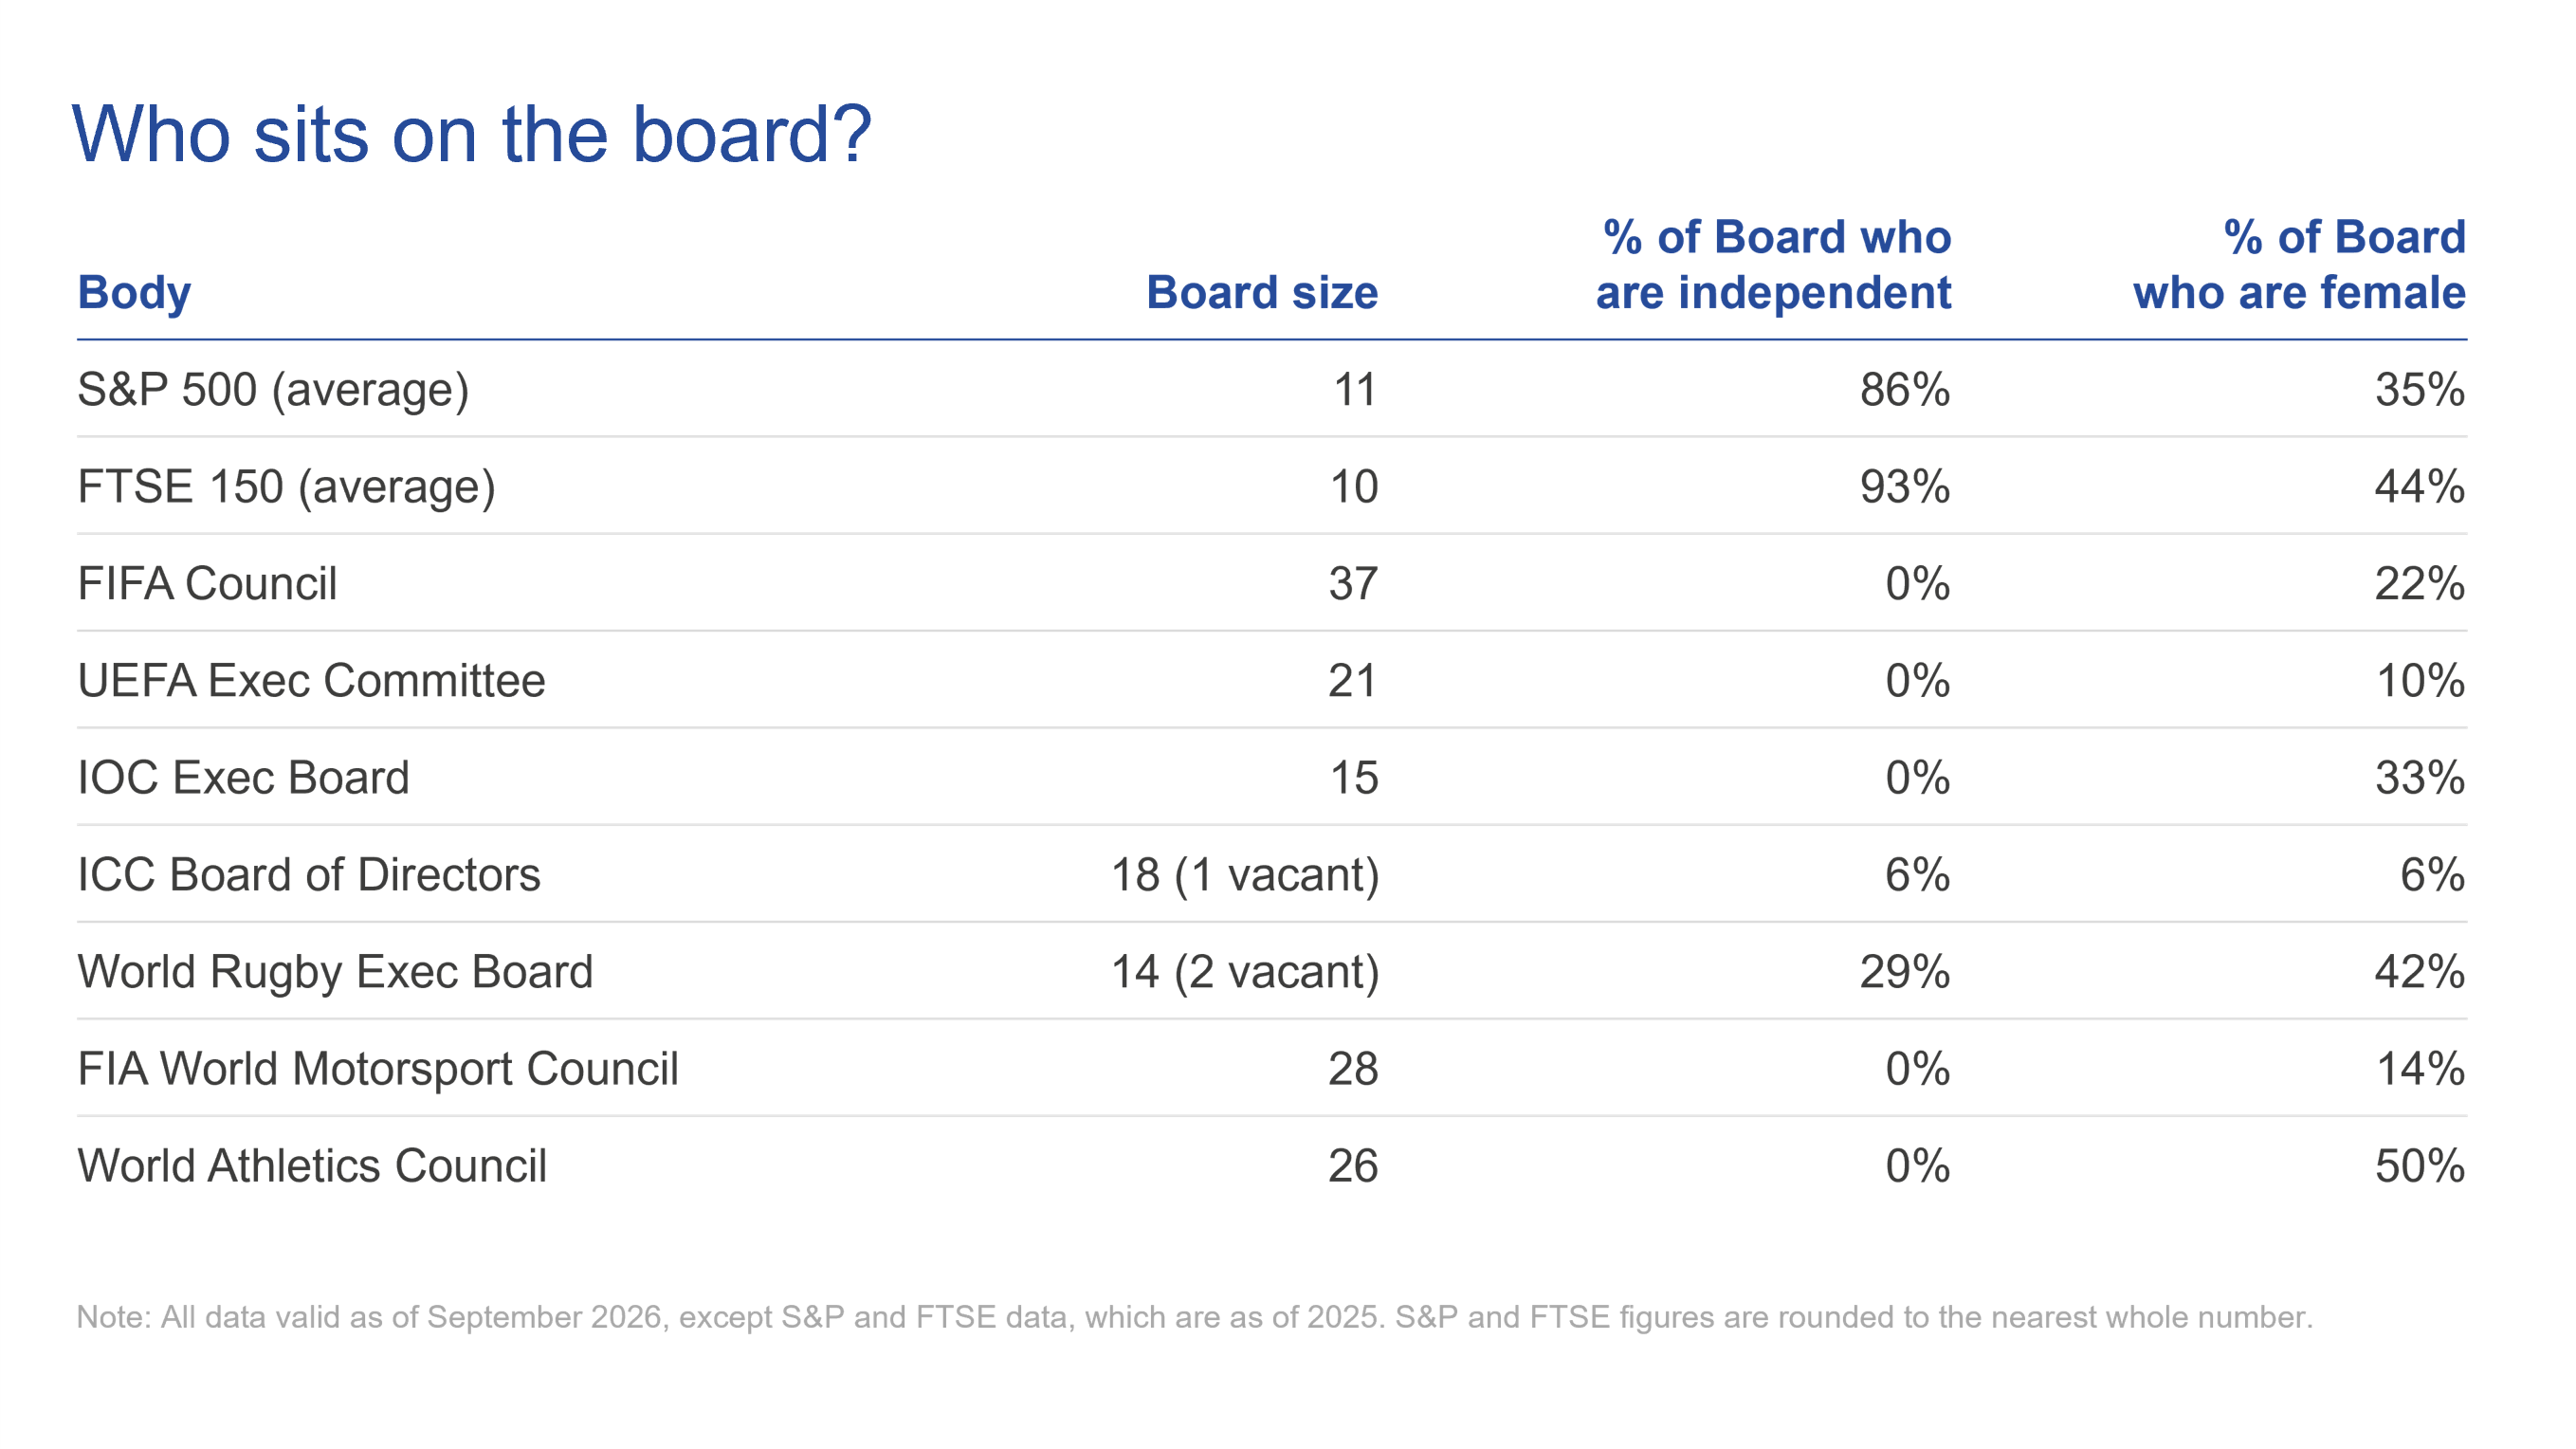
Some rules do not merely permit non-independence; they require it. The Union of European Football Associations’ statutes require executive committee candidates to hold active office within a member association. Independence, in the listed-company sense, is unavailable.
The pattern extends beyond football. The International Olympic Committee’s (IOC) Executive Board is drawn entirely from IOC members; the International Cricket Council created one independent seat in 2017.
Alternative models exist. After a 2022 independent review, World Rugby added three independent directors alongside elected, player and executive representatives.
Composition is also commercial. MSCI found companies with at least 30% female directors outperformed the rest by 19% in cumulative returns over five years. With women’s elite sport revenues set to top $3 billion in 2026, up 340% since 2022, federations whose boards reflect that audience are better placed to expand participation and build new fan bases.
Representation and independence need not be an either-or choice.
Sport already has a governance rulebook
The UK Code for Sports Governance requires bodies receiving over £1 million in public funding to cap boards at 12, appoint at least 25% independent non-executive directors, impose term limits and run a majority-independent nominations committee.
Table Tennis England had £9 million frozen after its members rejected the board appointment rules.
But it applies only to national governing bodies distributing public grants, not to international federations or commercial leagues funded by global media and sponsorship.
Commercial-scale sport may need a different model, but the same discipline.
Any institution underwriting a long-term asset asks three questions: Who decides? Who checks them? And what happens when things go wrong?
In a listed company, the answers are clear: management decides within a mandate set by a majority-independent board, and a statutory regulator can enforce resolution.
In a governing body, they are not. Who decides? An assembly of members, or a council drawn from them. Who checks them? A committee elected by that same assembly. And when things go wrong? Litigation, a competition authority, or a parliament, all arriving late and at cost.
Independence performs four functions:
- Challenging management on capital allocation
- Overseeing the auditor relationship
- Arbitrating conflicts between the organisation and its members
- Managing succession without a stake in the outcome
In a members’ association, all four fall to people whose duty is to the constituency that elected them. That tension is structural, not personal.
The hard question is what a board does when what is best for the sport over 20 years conflicts with what is best for the members who re-elect it in two.
Commercial decisions need commercial oversight
The gap is clearest when a governing body creates a commercial subsidiary, but leaves the parent’s governance unchanged.
One European football league spun its media rights into a separate company, selling a private investment firm a perpetual 13% claim on commercial revenues for €1.5 billion ($1.7 billion).
The commercial vehicle was new, but the board that approved it was not. When the media-rights market faltered, the investor’s claim remained.
In traditional capital markets, the permanence of that kind against so volatile a revenue stream is what an independent audit or risk committee exists to interrogate.
Every governance risk an investor cannot price becomes a risk they charge for. Governance is a growth question, not a compliance issue.
The path from $2.3 trillion to $3.7 trillion assumes capital keeps arriving. But pension funds, insurers and sovereign investors have long horizons and low risk tolerance: they need to see the controls to price the downside.
Weak governance does not stop capital entering sport. It makes it more expensive, more cautious and more conditional.
Sport can afford better governance. The question is whether it can keep affording the discount it pays without it.
The next phase is a design question
There is no single answer; the questions are ones of design:
- Who appoints independent directors in a federation without shareholders?
- How should athlete, club and national association representation be balanced?
- Should investors and sponsors impose higher standards through their conditions?
- Should sport lead reform, or will regulation ultimately be imposed?
As institutional capital moves deeper into sport, these questions get harder to leave unresolved.
Sport has become too large and too commercially complex for governance built for an earlier era. Its next phase of growth depends not only on attracting capital, but on building the confidence that keeps it there.
If you are an investor, government, league, team, federation, broadcaster or sponsor and want to help shape the future of sport, contact us at sports@weforum.org
Don't miss any update on this topic
Create a free account and access your personalized content collection with our latest publications and analyses.
License and Republishing
World Economic Forum articles may be republished in accordance with the Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 International Public License, and in accordance with our Terms of Use.
The views expressed in this article are those of the author alone and not the World Economic Forum.
Stay up to date:
Corporate Governance
Related topics:


Forum Stories newsletter
Bringing you weekly curated insights and analysis on the global issues that matter.
More on BusinessSee all

E. Richard Gold
September 30, 2026


